Your savings may be yours, but a notice period changes how quickly you can access the cash. Early withdrawal rules are worth checking before an emergency makes the decision for you.
A 32-day notice account sounds simple until you need the cash before the month is up. The money belongs to you, but access is not the same as swiping from an everyday savings account.
When you place notice, you tell the bank how much you want to withdraw. The 32-day clock then starts before that amount becomes available under the account terms. If an unexpected expense appears halfway through, knowing your bank’s early-access rules can save you from making a rushed decision.
The 32 days are about access, not ownership
You have not handed the money away for 32 days. You have agreed to a withdrawal notice period under the terms of the account.
Early access can be possible, depending on the product. FNB, for example, gives customers access after 32 days at no cost and permits earlier access at a cost under its 32-day notice account terms.
The awkward part is not the 32 days when life is calm. It is discovering that your emergency money has a waiting period after the expense has already happened.
Split urgent money from money that can wait
Before putting every spare rand behind a notice period, separate money you may need within hours or days from money you can leave untouched for longer. An emergency car repair, medical payment or broken appliance can require cash long before day 32.
Emergency savings can serve a separate purpose. You do not need every rand in one place. Money you may need quickly has a different purpose from money you can wait 32 days to access.
 Liz Thorne
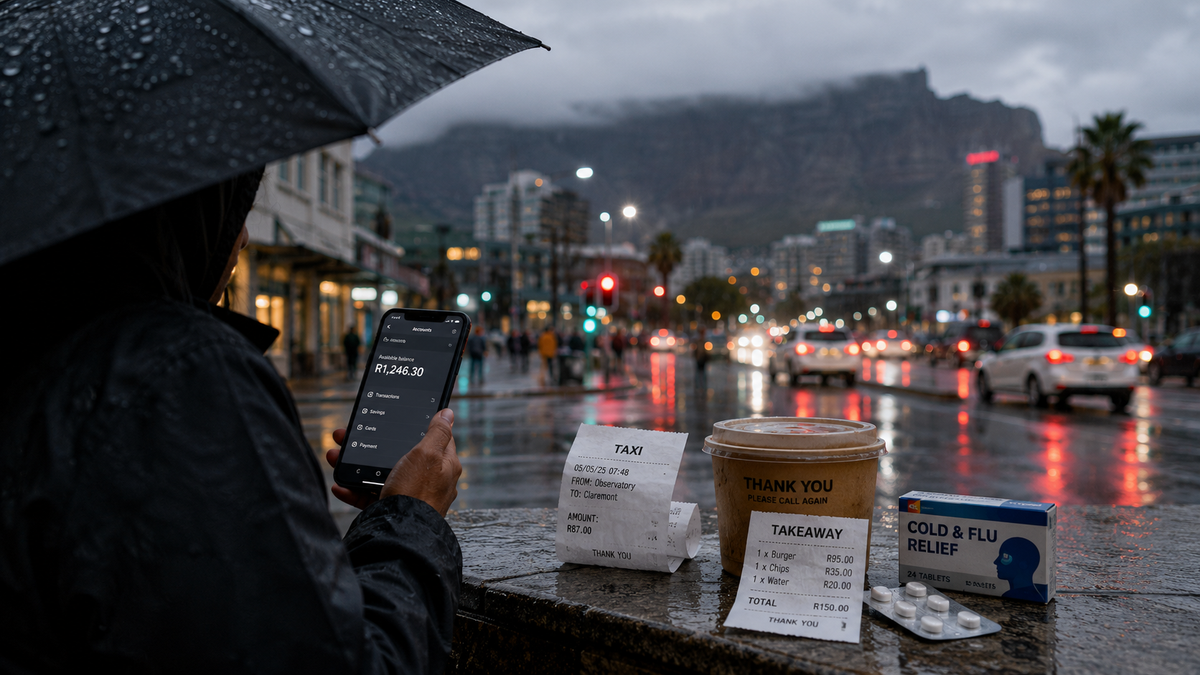
A useful check before transferring money into a notice account is whether you could manage if the amount was unavailable for the next 32 days. If the answer is no, consider leaving enough accessible elsewhere for expenses that cannot wait.
If you need the money before day 32
Check the account rules before cancelling notice, requesting early access or moving money. The bank may charge an early withdrawal fee, and the process can depend on the product you opened.
Look at the fee before deciding whether early access is worth it. A small urgent withdrawal and a full account closure can have different consequences under product rules, which is why the exact terms deserve a read before you confirm anything.
A notice account creates distance between savings and everyday spending. Distance can be useful when the money is meant for a future expense. Urgent costs do not respect a 32-day calendar.
A 32-day notice account requires that you trade instant access for a defined withdrawal process. Before you deposit, decide whether future-you could wait a month for that money. If not, the account may still work for part of your savings, not the part meant for tomorrow morning.
 Lynette Spencer
 Naomi Roebert
 Mariana Balt
Comments ()