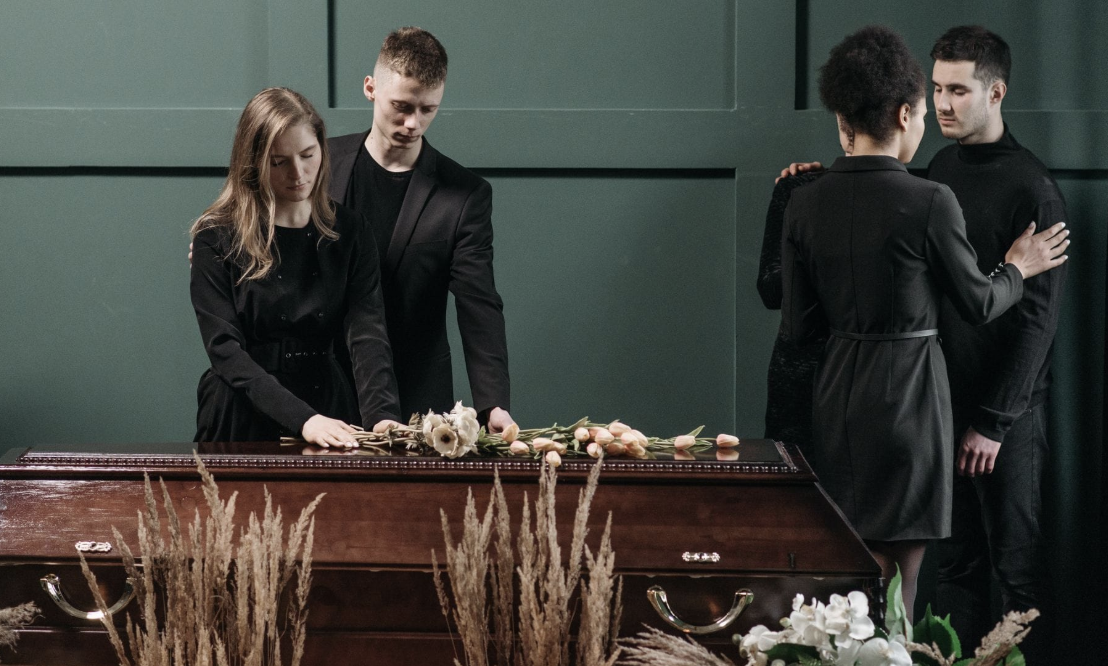
A funeral policy may be active while a waiting period still affects certain claims. Knowing what applies before a claim is submitted could save your family from an unpleasant surprise.
Funeral cover is one of those debit orders you would prefer never to test. If a claim follows soon after the policy started, the start date and cause of death become important because a waiting period may affect whether the benefit is payable.
A waiting period is a set period after cover begins during which certain claims are not covered. It does not mean every type of death is treated the same way.
Natural causes and accidents are treated differently
South Africa’s Policyholder Protection Rules restrict funeral-policy waiting periods for death from natural causes, with six months as the maximum period permitted under the rule. The rules do not permit a waiting period for a death caused by an accident.
A suicide exclusion is separate from the natural-cause waiting period. Under the same rules, such an exclusion may not exceed 12 months from the policy’s inception date.
A waiting period does not mean the policy provides no protection during its first months. The cause of death changes how the claim is treated, which is why the wording in your policy schedule is worth reading properly before anyone needs to claim.
Changing policies does not always restart the clock
Switching insurers does not automatically mean you must serve a fresh waiting period. Where you had similar funeral cover for the same insured lives and completed the previous waiting period, the rules restrict the new insurer from imposing another one if the replacement requirements are met.
If the earlier waiting period was incomplete, the new insurer may impose only the unexpired portion where the requirements apply. A policy that is renewed also cannot receive a new waiting period simply because a new term begins.
The monthly premium is only one part of an insurance decision. Looking at premium and excess on other cover shows why claim terms need the same scrutiny as the debit order.
 Liz Thorne
Check the dates before your family needs the cover
Read the policy schedule for the commencement date, waiting period, insured lives and cause-of-death provisions. If you replaced an older funeral policy, retain proof of the previous cover and ask the new insurer to confirm in writing how any waiting period was treated.
A lapse also needs a closer look. The rules protect certain reinstated funeral policies from a fresh waiting period, while a new policy taken with the same insurer within two months of a lapse has specific protections depending on whether the original waiting period had been completed.
A funeral policy is bought for a future day nobody wants to plan around. Knowing the waiting period gives your family one less uncertainty if a claim follows soon after cover begins. The policy schedule is the most important document, not your memory of the sales pitch.
🎶 𝖣𝖾𝗄𝖺𝖽𝖾𝗌 𝗌𝖾 𝗈𝗈𝗋𝗌𝗉𝗋𝗈𝗇𝗄𝗅𝗂𝗄𝖾 𝖠𝖿𝗋𝗂𝗄𝖺𝖺𝗇𝗌𝖾 𝖽𝗂𝗀𝗄𝗎𝗇𝗌 𝗄𝗋𝗒 𝗇𝗎𝗐𝖾 𝗅𝖾𝗐𝖾 𝖽𝖾𝗎𝗋 𝗆𝗎𝗌𝗂𝖾𝗄. 𝖶𝖾𝗅𝗄𝗈𝗆 𝗂𝗇 𝗆𝗒 𝖪𝗅𝖾𝗂𝗇 𝖪𝖺𝗋𝗈𝗈 - 𝖡𝗈𝗅𝖺𝗇𝖽𝗌𝖾 𝖻𝗂𝗇𝗇𝖾𝗄𝖺𝗆𝖾𝗋.
Comments ()